


Overview
And Tightens the Forex Screws
The April 2026 policy kept the repo at 5.25 percent while widening forex scrutiny to corporate treasuries
A Net Open Position (NOP) is the difference between a bank's foreign-currency assets and liabilities at the close of each trading day; it captures the bank's directional exposure to currency movements. On 27 March 2026, the Reserve Bank of India capped banks' end-of-day NOP in the domestic foreign-exchange market at 100 million US dollars. On 1 April 2026, the RBI extended its scrutiny beyond banks to corporate treasuries, requesting data on the extent of arbitrage exposure. On 8 April 2026, the Monetary Policy Committee held the repo rate at 5.25 percent, completing a three-move April playbook to defend the rupee under capital-outflow stress.
Why this is in the news on 8 April 2026
The three-move April playbook
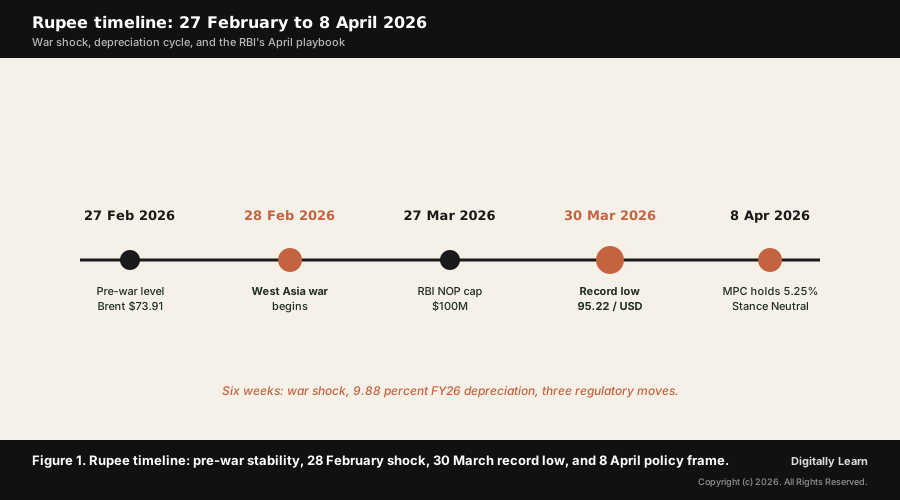
On 8 April 2026, the Reserve Bank of India held the repo rate unchanged at 5.25 percent in its first Monetary Policy Committee meeting of the new financial year. The headline rate decision sits alongside two earlier regulatory moves that together describe a three-step April playbook to defend the rupee under capital-outflow stress.
Definition: A Net Open Position is a bank's end-of-day directional foreign-currency exposure (assets minus liabilities). A corporate treasury is the function inside a non-bank firm that manages its foreign-exchange exposures through hedging, ensuring that earnings and cash flows are not hit by currency swings.
Three moves define the April playbook:
- (i) 27 March 2026: RBI capped banks’ net open positions in the domestic forex market at 100 million US dollars at the end of each day, forcing several lenders to unwind arbitrage trades.
- (ii) 1 April 2026: RBI issued a data call to corporate treasuries, assessing the extent of arbitrage exposure beyond banks. The exercise targets information, not immediate action; an unwind could follow if arbitrage positions are confirmed.
- (iii) 8 April 2026: MPC held the repo rate at 5.25 percent and retained the Neutral stance held since June 2025. The pause signals that currency defence will rely on regulatory and unconventional tools, not rate action.
Why the playbook matters for India's external balance
Rupee under capital-outflow stress
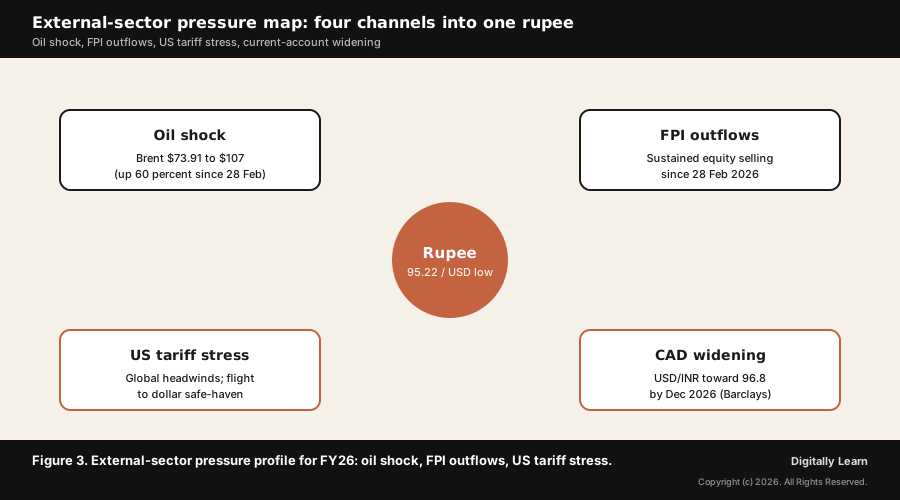
Why it matters: The rupee has been under sustained pressure since the 28 February 2026 West Asia war began. Across FY26 the currency depreciated by 9.88 percent against the US dollar, its steepest annual fall in 14 years, hitting a record intra-day low of 95.22 per dollar on 30 March. Brent crude has surged from 73.91 US dollars per barrel on 27 February to about 107 US dollars in early April, lifting India's import bill at exactly the moment foreign portfolio investors are pulling out.
The capital-outflow component runs through foreign portfolio investor equity sales amid US tariff actions and global headwinds, while the import-bill component runs through the oil shock. Combined, the two pressures widened the current-account gap and tested the rupee's support level. Without intervention, the rupee could weaken further; Barclays estimates USD/INR drift toward 96.8 by December 2026.
The arbitrage circuit the RBI is now scrutinising works like this: banks buy dollar forwards cheaply in India and sell them at a premium abroad, profiting from the price gap while keeping risk balanced on paper. Jefferies, in a 29 March report, noted that the onshore derivative market is dominated by larger banks with gross onshore positions of 30 to 40 billion US dollars that largely offset each other. Some of that arbitrage may have been passed on to corporate treasuries, hence the data call.
Significance for India's regulatory architecture
How the perimeter expansion changes the toolkit
What is the significance of this regulatory perimeter expansion: The April playbook sits at three doctrinal threads that Mains aspirants should track together.
- (i) Regulatory perimeter widens beyond banks. Historically the RBI’s forex toolkit acted on banks only, through net open position limits and intervention sales. Extending the data call to corporate treasuries marks a perimeter expansion: non-bank financial actors are now under direct regulatory observation for forex positioning.
- (ii) Currency management decoupled from rate policy. Despite the rupee at a record low, the 8 April MPC chose to hold the repo rate. The signal: rate policy will respond to inflation and growth fundamentals; currency volatility will be managed by regulatory and unconventional tools (NOP caps, hedge-rebooking bans, related-party rules, intervention).
- (iii) Speculative arbitrage circuit identified. The arbitrage trade (buy dollar forwards onshore cheap, sell offshore at premium) was a source of one-way pressure on the rupee in volatile sessions. Capping NOP and tracking corporate-treasury exposure cuts off the supply of speculative positioning without raising borrowing costs for the real economy.
Distinguishing features of the April toolkit
Three regulatory tools in one view
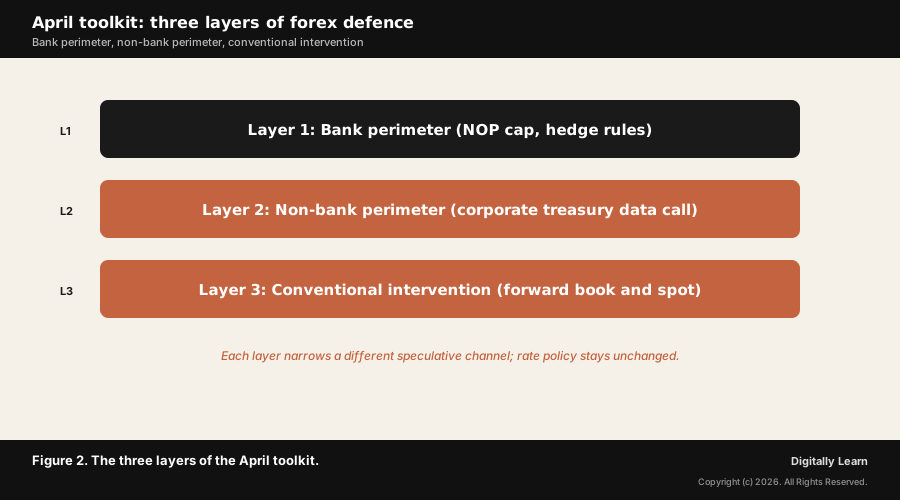
Toolkit architecture: The three regulatory moves act on different layers of the forex market. The table below maps each tool to the participant it constrains, the mechanism it disrupts, and the expected near-term effect.
| Tool | Participant constrained | Mechanism disrupted | Near-term effect |
|---|---|---|---|
| Net Open Position cap (100 million USD end-of-day) | Scheduled commercial banks operating in the domestic forex market | Onshore-offshore dollar-forward arbitrage carried on bank books | Banks unwind speculative positions; rupee one-way pressure eases briefly |
| Hedge rebooking ban and related-party rules | Banks and corporate clients using hedge contracts to roll forex bets | Repeated rebooking of hedges as a vehicle for speculative positioning | Speculative hedging access narrows; legitimate hedging continues |
| Corporate treasury data call (1 April) | Non-bank corporates holding large arbitrage exposure | Off-bank-balance-sheet arbitrage positions invisible to RBI | Regulator gains visibility; potential unwind if exposure is confirmed |
| Conventional intervention (forward book and spot) | All onshore market participants | Disorderly rupee depreciation | Smooth rupee volatility without exhausting reserves |
Distinguishing features: Three architectural moves separate the April playbook from earlier RBI rupee-defence cycles:
- (i) Quantitative cap on bank positioning. A hard 100 million US dollar end-of-day NOP is the first numerical guard-rail of its kind in recent cycles, replacing softer prudential guidance with a binding limit.
- (ii) Information-first approach on non-banks. The corporate-treasury exercise is framed as a data call, not a directive. The RBI gains visibility before deciding whether unwind action is required.
- (iii) Rate policy decoupled. Earlier defence cycles often combined rate hikes with regulatory action. The 8 April hold makes a deliberate institutional choice: regulatory and unconventional tools first, rate action only if inflation expectations slip.
Observable outcomes the playbook is producing
Three trackable outcomes by Q2 FY27
Observable outcomes: The April playbook sets up three trackable outcomes that an aspirant should keep in working memory through the financial year.
- (a) Macroeconomic outlook revision. At the April policy the RBI projected FY27 GDP growth at 6.9 percent, down from its February estimate of 7.4 percent, and FY27 CPI inflation at 4.6 percent, with upside risks flagged from energy prices and a weak rupee. Private forecasts moved in the same direction: Kotak revised growth down to 6.5 percent and several houses cut FY27 GDP into a 6.2 to 6.9 percent band as the oil shock fed through.
- (b) Bond yields stay biased above 7 percent. MUFG expects India’s 10-year yield to stay biased further above 7 percent amid fiscal concerns and global factors. Liquidity management will lean on variable rate repo and variable rate reverse repo operations to keep conditions broadly neutral while managing borrowing pressures.
- (c) Rupee trajectory bracketed. Barclays estimates USD/INR could weaken toward 96.8 by December 2026, reflecting a widening current account deficit and global headwinds. The April playbook is expected to slow the drift, not reverse it.
Contemporary linkages
How the April playbook links to the wider macro file
Contemporary linkages: The April playbook is the opening move of a multi-month rupee-defence cycle that recurs in this file.
- (i) West Asia war and the oil-price channel. The 28 February 2026 war pushed Brent crude up over 60 percent. India imports about 85 percent of its crude requirement; a sustained price shock widens the current account gap and feeds imported inflation. The April playbook is downstream of this oil shock.
- (ii) Foreign portfolio investor outflows under US tariff stress. FY26 saw sustained FPI selling amid global headwinds including US tariffs. Capital outflows on the financial account, combined with the wider current-account gap, set up the one-way rupee pressure that the April playbook responds to.
- (iii) Subsequent rupee-defence cycle (May 2026). The April moves were followed by a renewed rupee-intervention phase in May 2026, when the central bank stepped in again to manage volatility. For the May reading, see the sibling briefing Indian Rupee Depreciation and RBI Intervention (May 2026) on this site.
UPSC Relevance
Where this fits in the UPSC-CSE syllabus
Where it fits: This topic sits primarily under General Studies Paper III: Indian Economy, specifically the heads of monetary policy, banking sector regulation, and external sector and balance of payments. It also touches government budgeting and effects of economic policies on a wide range of stakeholders.
For Prelims, the high-yield facts cluster across the toolkit, the market response, and the policy stance:
- NOP cap: 100 million US dollars end-of-day on banks in the domestic forex market, effective 27 March 2026.
- Corporate-treasury data call: 1 April 2026, extending the regulatory perimeter to non-bank actors.
- MPC decision: 8 April 2026, repo rate held at 5.25 percent, stance Neutral retained since June 2025.
- 2025 rate cycle: cumulative cuts of 125 basis points across 2025, final cut of 25 bps in December 2025.
- Rupee record low: 95.22 per US dollar (intra-day) on 30 March 2026; FY26 depreciation of 9.88 percent, the steepest in 14 years.
- Oil price shock: Brent crude from 73.91 US dollars on 27 February to about 107 US dollars in early April 2026 (up 60 percent).
- Jefferies derivative-market estimate: 30 to 40 billion US dollars gross onshore positions held by larger banks.
- Liquidity tools: Variable Rate Repo (injects) and Variable Rate Reverse Repo (absorbs); open-market operations on government securities.
For Mains, two framings recur. First, the institutional perimeter expansion: how the RBI's regulatory reach now covers banks plus corporate treasuries plus non-bank actors, and what that means for monetary-policy transmission. Second, the decoupling of rate policy from currency management: the textbook argument that rate hikes defend currencies has been deliberately overridden in favour of regulatory tools and unconventional intervention, with the rationale that rate action would damage growth without resolving the capital-flow imbalance.
- Common Prelims trap. The 100 million US dollar cap applies to end-of-day net open positions of banks in the domestic forex market, not a per-trade limit or an intraday cap. Students often misstate the scope.
- Common Mains trap. Treating the rupee record low as the trigger misreads the doctrine. The trigger was the dual capital-outflow plus oil-shock combination from 28 February onward; the record low is the symptom. The framing must lead with the macro driver, not the headline number.
- Cross-cutting trap. Variable rate repo (VRR) injects liquidity into the system; variable rate reverse repo (VRRR) withdraws liquidity. Mixing these two is a frequent error in liquidity-management questions.
Previous Year UPSC-CSE Questions By the end you will be able to draft model answers for the following UPSC questions. Each question carries a collapsible framework showing how to approach it in the exam.
- UPSC Prelims 2025Which of the following are the sources of income for the Reserve Bank of India?
- Buying and selling Government bonds
- Buying and selling foreign currency
- Pension fund management
- Lending to private companies
- Printing and distributing currency notes
Select the correct answer using the code given below:
How to approach this Prelims question
Approach: Verify each statement against the RBI's actual income-generating activities; eliminate those that are NOT RBI functions.
Trap to watch: Statement III (Pension fund management) and IV (Lending to private companies) are not RBI functions; pensions are managed by PFRDA-regulated entities, and RBI does not lend directly to private companies.
Key facts to recall:
- RBI's primary income sources are interest on government bonds (open market operations), gains on foreign-currency transactions; UPSC's official key does not count printing and distributing currency notes (statement V) as an income source.
- RBI does not manage pension funds; PFRDA regulates the National Pension System.
- RBI does not lend to private commercial entities; the lender-of-last-resort function is to scheduled commercial banks.
Answer signal: Statements I and II are correct; option (a) is the answer, as per UPSC's official answer key.
- UPSC Mains 2024 GS-IIIWhat are the causes of persistent high food inflation in India? Comment on the effectiveness of the monetary policy of the RBI to control this type of inflation.
How to structure the answer in the exam
Introduction: One-line statement on persistent food inflation as primarily a supply-side phenomenon, with the April 2026 oil-shock cycle as a topical illustration.
Body (sub-themes to develop):
- Causes: monsoon variability, supply-chain disruptions, energy-price pass-through (Brent crude shock since 28 February 2026), administered price interventions, and global commodity cycles.
- Effectiveness of monetary policy: rate transmission to food-price formation is weak because food markets respond to supply not credit; the 8 April 2026 MPC chose to hold the repo rate at 5.25 percent precisely because the inflation shock was supply-side.
- Complementary tools: open-market operations, liquidity-management tools (VRR / VRRR), regulatory tightening on speculative forex circuits (the April 2026 NOP cap and corporate-treasury data call), and structural fiscal-supply-side coordination with the Ministry of Agriculture and Consumer Affairs.
Conclusion: Two-line synthesis arguing monetary policy is one instrument in a multi-tool kit; food inflation requires complementary fiscal and supply-side action, not rate hikes alone.
Sources and Further Reading
- LiveMint: To defend rupee, RBI widens forex lens beyond banks to corporate treasuries (1 April 2026)
- LiveMint: RBI likely to hold rates as war-driven risks cloud inflation and growth outlook (6 April 2026 preview)
- LiveMint: RBI shuns hawkish signal, keeps rates unchanged amid war shock (8 April 2026)
- Reserve Bank of India: monetary policy statements and circulars
- Ministry of Finance, Government of India: external sector statements
- Press Information Bureau: RBI press-release index
- Wikipedia: Reserve Bank of India (institutional overview)
- Wikipedia: Indian rupee (currency overview and exchange-rate context)
Editorial Disclaimer
This article is compiled from the reference materials listed in the Sources section. It is an explainer for UPSC preparation and is not a substitute for primary documents (NCERTs, GoI ministry releases, IMD bulletins, RBI / CEA / MoEFCC publications, and Standing-Committee reports).


