


Overview
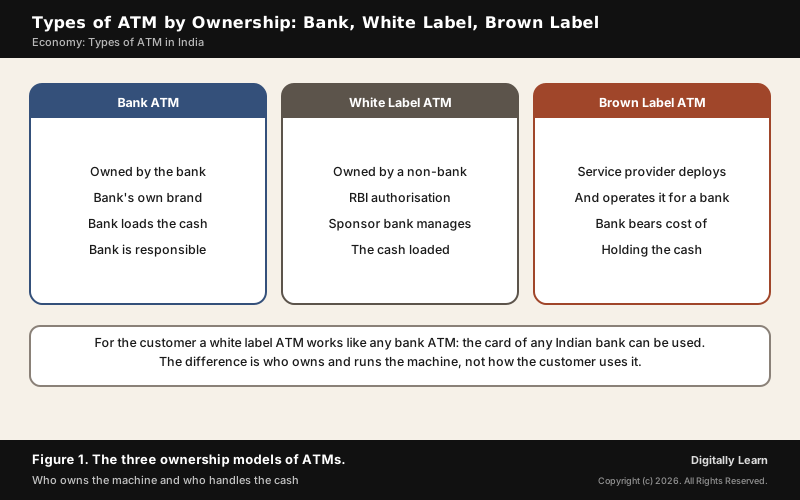
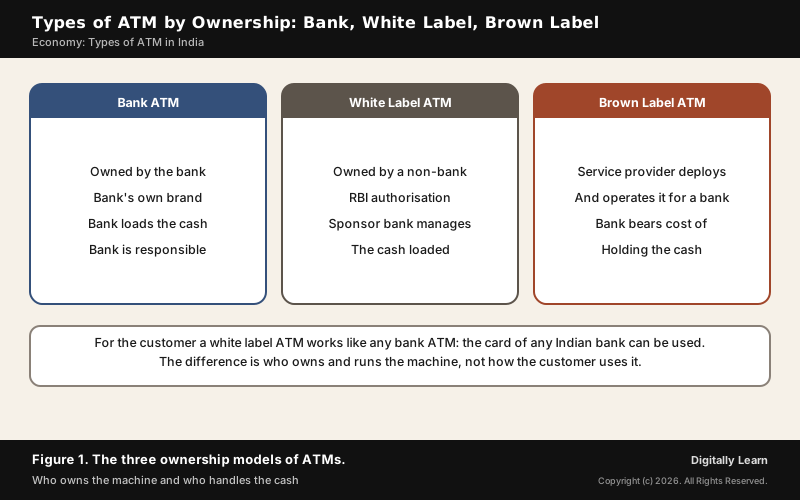
The types of ATM in India are classified in three ways. By ownership there are bank ATMs, white label ATMs owned and run by RBI-authorised non-banks, and brown label ATMs deployed and operated for banks by service providers. By location they are on-site or off-site, and by function they range from cash dispensers to cash recyclers and portable micro ATMs.
ATM Meaning and Classification: Ownership, Location and Function
What Is an ATM and How Many Types Are There?
An ATM, or Automated Teller Machine, is a computerised machine that lets bank customers reach their accounts to withdraw cash and carry out other financial and non-financial transactions without visiting a branch. What it draws on is a demand deposit: money in a bank account that can be withdrawn on demand, which is why such deposits are called demand deposits. India's ATMs can be classified in three ways, and exam questions usually mean the first:
| Basis | Types |
|---|---|
| Ownership | Bank ATM, white label ATM, brown label ATM |
| Location | On-site (at a branch) and off-site (elsewhere) |
| Function | Cash dispenser, cash recycler, micro ATM |
How Many ATMs Are There in India?
The first ATM in India was set up by HSBC in Mumbai in 1987, and in the next ten years about 1,500 more followed. By July 2026 banks had deployed 1,36,337 ATMs and cash recyclers on-site and 73,475 off-site, according to the RBI's bank-wise statistics, along with 13,28,246 micro ATMs.
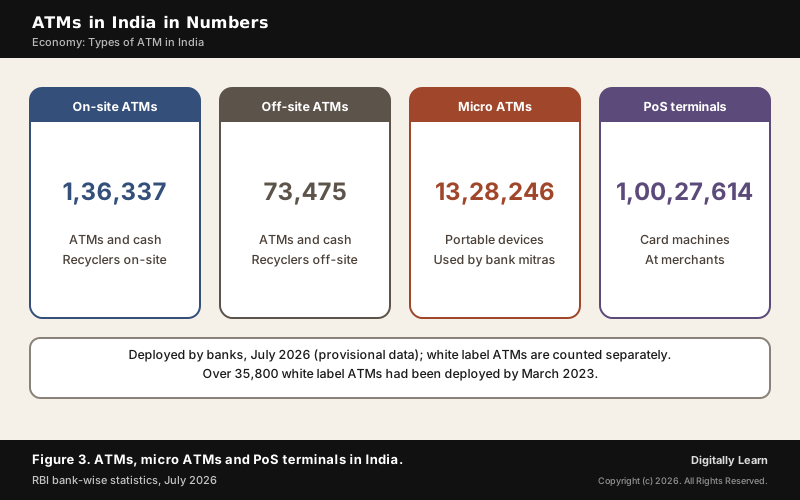
White label ATMs are counted separately. More than 35,800 had been deployed by March 2023, from 11,706 at the end of 2015. The NPCI network that links them all connected more than 2.55 lakh ATMs, including cash deposit machines and recyclers, in January 2022.
| Bank group | On-site | Off-site | Total |
|---|---|---|---|
| Public sector (12) | 83,317 | 51,342 | 1,34,659 |
| Private sector (21) | 49,105 | 21,738 | 70,843 |
| Small finance (11) | 3,345 | 30 | 3,375 |
| Foreign (14) | 570 | 365 | 935 |
| All banks | 1,36,337 | 73,475 | 2,09,812 |
Public sector banks own almost two-thirds of the network, and State Bank of India alone had 65,175 ATMs and recyclers, 28,841 on-site and 36,334 off-site. Payment banks, which the RBI's table also lists, had no ATMs but did have micro ATMs: Airtel Payments Bank alone had 1,65,075.
Types of ATM by Ownership: White Label and Brown Label ATMs
White Label ATMs (WLAs): Meaning, RBI Rules and Operators
ATMs set up, owned and operated by non-banks are called white label ATMs, and their operators white label ATM operators (WLAOs). The RBI allowed them from 20 June 2012 to spread ATMs beyond Tier I and II centres, where most bank ATMs stood, into Tier III to VI centres, towns and villages with populations below 50,000.
- Who can apply: A non-bank company with a net worth of at least Rs 100 crore, kept at all times, authorised under the Payment and Settlement Systems Act, 2007.
- Sponsor bank: Cash management at a WLA is the sponsor bank’s responsibility; the WLAO owns the cash but neither it nor its agents may access it.
- Rural targets: Three schemes set minimum roll-outs with ratios of 3:1, 2:1 or 1:1 between Tier III to VI and Tier I to II centres, and at least 10 per cent in Tier V and VI.
- No direct charges: A WLA earns a fee from banks for use of the machine and may not charge the bank’s customer directly.
- What it cannot do: Sell mobile reload vouchers, and at first it could not accept deposits.
The rules were eased to make WLAs viable. From 2016 operators could source cash from retail outlets, and a review of 7 March 2019 let them buy wholesale cash directly from the RBI and currency chests, source cash from any scheduled bank, offer bill payment and interoperable cash deposit, and show advertisements. Authorisation has been on tap since October 2019, and four non-bank entities were operating WLAs in 2023.
White Label ATM Operators in India
The early white label network was built by a handful of companies. A government reply of November 2016 gave the count by operator and by type of centre, and it shows the rural tilt the RBI's ratios were meant to produce:
| Operator (2016) | Rural | Total |
|---|---|---|
| Tata Communications Payment Solutions | 3,212 | 8,255 |
| BTI Payments | 2,028 | 3,797 |
| Hitachi Payment Services | 298 | 1,040 |
| Vakrangee | 90 | 304 |
| Riddhi Siddhi Bullions | 14 | 204 |
| Muthoot Finance | 22 | 184 |
| AGS Transact Technologies | 1 | 73 |
| All white label ATMs | 5,665 | 13,857 |
Rural and semi-urban centres held 10,214 of the 13,857 machines. Foreign direct investment of up to 100 per cent in white label ATMs has been allowed under the automatic route since September 2015. When a transaction fails at a WLA, the card-issuing bank has the primary duty to resolve the customer's complaint, with the sponsor bank supplying the records.
Brown Label ATMs and How They Differ from White Label ATMs
A brown label ATM belongs to the bank's network but is deployed and operated for the bank by a managed service provider. The RBI's Committee to Review the ATM Interchange Fee Structure described brown label ATM operators as managed service providers that deploy and operate ATMs for banks, managing about 30 per cent of all ATMs in the country, excluding white label ATMs. In this model the cost of holding the cash is borne by the bank.
Banks can do this because the RBI permits them to outsource financial services under its guidelines on managing risks in outsourcing, issued in 2006 and 2015. The bank keeps the responsibility: it must carry out due diligence on the service provider, write the terms into a contract, and audit the arrangement.
The difference from a white label ATM is who owns the machine and who answers to the RBI for it:
| Point | White label ATM | Brown label ATM |
|---|---|---|
| Owned and run by | A non-bank (WLAO) | A service provider, for a bank |
| Authority | RBI authorisation, PSS Act 2007 | Bank's outsourcing contract |
| Cash | WLAO's; sponsor bank manages | Bank bears the cost of holding it |
| Earns from | Fees paid by banks | The bank's contract |
| Aim | ATMs in Tier III to VI centres | Bank outsources the operation |
Types of ATM by Location and Function
On-Site and Off-Site ATMs, Cash Recyclers and Micro ATMs
By location, an ATM is on-site when it stands on a bank's premises and off-site when it stands elsewhere, at a market, a station or a fuel pump. On-premises ATMs are usually more advanced, multi-function machines that complement a branch, while off-premises machines serve a simple need for cash and are generally cheaper single-function devices.
The RBI's monthly statistics report the two separately for every bank. In July 2026 banks had nearly twice as many ATMs on-site (1,36,337) as off-site (73,475). White label ATMs are not part of these bank figures.
By function, ATMs go beyond cash dispensers:
- Cash recycler machines (CRMs): Accept deposits as well as dispense cash; the RBI’s charge rules apply to them except for cash deposits.
- Micro ATMs: Portable devices; bank mitras in rural areas carry them from place to place. Banks had 13,28,246 in July 2026.
- Card-less withdrawal: The RBI has also allowed withdrawals at ATMs without a card.
ATMs also do much more than give cash: account information, cash deposit, bill payment, mini statements, PIN change and cheque-book requests. Any card issued by a bank in India, debit, credit or prepaid, can be used at any ATM or white label ATM in the country, as the issuer permits.
ATM Colour Labels: Green, Pink, Yellow and Orange Label ATMs
Are Green, Pink, Yellow and Orange Label ATMs Official?
Only two colour labels have a basis in the RBI's own documents. White label is an official category, defined in the RBI's guidelines and FAQs. Brown label appears in the RBI committee report as a class of ATM operator. Neither is about the machine's paint; both are about who owns and runs it.
Lists in study material also name green, pink, yellow and orange label ATMs, each tied to a purpose. None of the RBI's circulars, FAQs or statistics uses these labels, so the meanings below are only what those lists say. They are given here because students meet them, not because they are official.
| Label in study lists | Meaning those lists give | Official status |
|---|---|---|
| Green label | ATMs for agricultural transactions | Not an RBI category |
| Pink label | ATMs for women only | Not an RBI category |
| Yellow label | ATMs for e-commerce transactions | Not an RBI category |
| Orange label | ATMs for share transactions | Not an RBI category |
| White label | Owned and run by an RBI-authorised non-bank | Official (RBI) |
| Brown label | Run for a bank by a managed service provider | Used in an RBI committee report |
In an answer, treat white and brown as the ownership types, and add that the other colours are labels from study material with no RBI definition.
ATM Network, Charges and Customer Rights
NPCI and the National Financial Switch
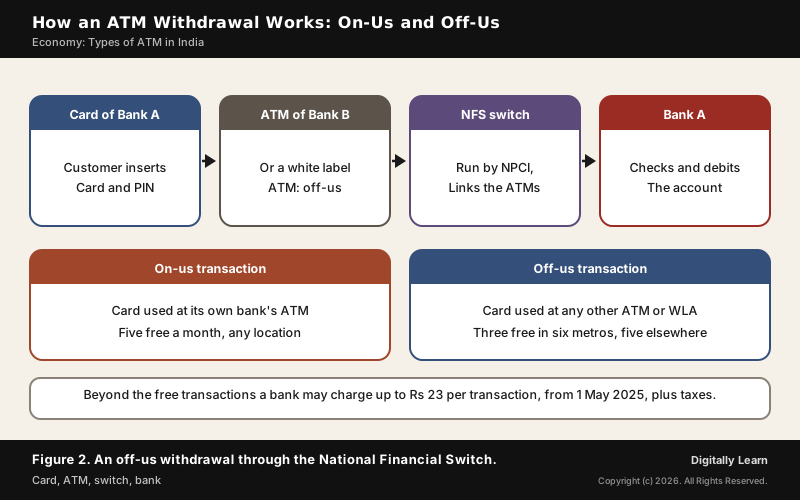
Cards of one bank work at another bank's ATM because the ATMs are linked. The National Financial Switch (NFS) is the largest network of shared ATMs in India. It was developed by the Institute for Development and Research in Banking Technology (IDRBT) in 2004 and is run by the National Payments Corporation of India (NPCI), an initiative of the RBI and the Indian Banks' Association under the Payment and Settlement Systems Act, 2007.
Shared networks came early. In 1997 the Indian Banks' Association set up Swadhan, the first network of shared ATMs in India, which let cardholders withdraw cash at any ATM in the network. The NFS built by IDRBT in 2004 took over that role, and in January 2022 its 1,203 members included four white label ATM operators.
A transaction at the card-issuing bank's own ATM is an on-us transaction; one at any other ATM or a white label ATM is off-us. For off-us use, the ATM owner is paid an interchange fee, which is now decided by the ATM network.
ATM Charges and Free Transactions: RBI Rules
The RBI sets the minimum number of free ATM transactions for savings account holders:
- Own bank’s ATM: Five free financial transactions a month at any location; non-cash transactions are free without limit.
- Other banks’ ATMs in six metros: Three free transactions a month in Bengaluru, Chennai, Hyderabad, Kolkata, Mumbai and New Delhi.
- Other banks’ ATMs elsewhere: Five free transactions a month.
- Beyond the free limit: Up to Rs 23 per transaction from 1 May 2025, plus taxes.
The cap has risen over time: Rs 20 from August 2014, Rs 21 from 1 January 2022 and Rs 23 from 1 May 2025. Banks set their own charges for cash withdrawn with credit cards or abroad, and the free-transaction rules do not apply to Basic Savings Bank Deposit Accounts, which have their own withdrawal conditions.
Because the free limit differs between metro and non-metro locations, every ATM must show clearly, by a message on the screen, a sticker or a poster, whether it is in a metro or a non-metro location.
Interchange Fee and the Cost of Running an ATM
Every off-us withdrawal costs the card-issuing bank an interchange fee, paid to the bank or operator that owns the ATM. For years the RBI fixed it: it was raised in August 2021 from Rs 15 to Rs 17 for a financial transaction and from Rs 5 to Rs 6 for a non-financial one, the first change since August 2012. Since the March 2025 update the fee is decided by the ATM network.
The fee exists because ATMs are expensive to run. A committee under the chief executive of the Indian Banks' Association found a monthly cost of Rs 83,700 to Rs 95,000 per ATM for public sector banks other than SBI, and about Rs 70,565 for brown label operators, rising to about Rs 83,700 after new security rules such as anti-skimming and whitelisting solutions. When the RBI raised the fees in 2021 it cited the increasing cost of ATM deployment and maintenance.
Failed ATM Transactions: Refund and Compensation
If an ATM debits the account but gives no cash, the card-issuing bank must re-credit the account within T plus 5 calendar days, where T is the day of the transaction. For each day of delay beyond that it must pay the customer Rs 100, without the customer having to claim it, as compensation.
Failed transactions caused by the bank or the machine, such as a hardware fault or no notes in the ATM, are not counted among the free transactions and cannot be charged. A customer who gets no remedy from the bank within 30 days can go to the Reserve Bank Integrated Ombudsman Scheme.
Security rules sit alongside. Banks had to replace all magnetic stripe cards with EMV chip and PIN cards by 31 December 2018, since a chip card stores its data in a chip rather than a stripe. The RBI also tells customers to check for extra devices attached to an ATM, which can be fitted to capture card data, and never to share the PIN, even with a bank official.
Previous Year UPSC-CSE Questions
Previous Year UPSC-CSE Questions By the end you will be able to draft model answers for the following UPSC questions. Each question carries a collapsible framework showing how to approach it in the exam.
- UPSC Prelims 2018 Prelims-GSWhich one of the following links all the ATMs in India ?
How to approach this Prelims question
Approach: Identify the body that runs the shared ATM network. The National Financial Switch, India's largest shared ATM network, was built by IDRBT in 2004 and has been run by the National Payments Corporation of India since. The RBI regulates payment systems and the Indian Banks' Association co-founded NPCI, but neither runs the switch.
Trap to watch: The RBI regulates; the IBA co-founded NPCI; neither runs the switch.
Key facts to recall:
- (a) Indian Banks' Association: wrong. It co-founded NPCI with the RBI but does not run the ATM switch.
- (b) National Securities Depository Limited: wrong. It is a depository for securities, not an ATM network.
- (c) National Payments Corporation of India: right. It runs the National Financial Switch that links the ATMs.
- (d) Reserve Bank of India: wrong. It regulates, but the network itself is run by NPCI.
Answer signal: NPCI links all ATMs through the National Financial Switch, so option (c) is the answer.
- UPSC Prelims 2017 Prelims-GSConsider the following statements:
- The National Payments Corporation of India (NPCI) helps in promoting financial inclusion in the country.
- NPCI has launched RuPay, a card payment scheme.
Which of the above statements is/are correct?
How to approach this Prelims question
Approach: Test NPCI's role in inclusion and its card scheme. NPCI, an initiative of the RBI and the Indian Banks' Association, builds shared payment networks that widen access to banking, so statement 1 holds. RuPay is NPCI's own card payment scheme, so statement 2 holds.
Trap to watch: Both statements are true.
Key facts to recall:
- (a) 1 only: wrong. It leaves out RuPay, which NPCI launched.
- (b) 2 only: wrong. It leaves out NPCI's role in financial inclusion.
- (c) Both 1 and 2: right. NPCI promotes inclusion and runs RuPay.
- (d) Neither 1 nor 2: wrong. Both statements are true.
Answer signal: Both statements are correct, so option (c) is the answer.
Sources and Further Reading
- RBI: FAQs on ATM / White Label ATM (updated 4 July 2025)
- RBI: Usage of ATMs and Cash Recycler Machines, Review of Interchange Fee and Customer Charges (updated 28 March 2025)
- RBI: Guidelines for White Label ATMs in India (20 June 2012)
- RBI: White Label ATMs in India, Review of Guidelines (7 March 2019)
- RBI: Report of the Committee to Review the ATM Interchange Fee Structure
- RBI: Bank-wise ATM/POS/Card Statistics, July 2026
- PIB: White Label ATMs to drive ATM penetration (25 July 2023)
- PIB: White Label ATMs (26 February 2016)
- PIB: ATM operating agencies of public sector banks (25 November 2016)
- Indian Economic Service, Arthapedia: White Label ATMs
- NCERT: Understanding Economic Development (Class X), Money and Credit
- Wikipedia: White-label ATM
- Wikipedia: Automated teller machine
- Wikipedia: National Financial Switch
- Wikipedia: National Payments Corporation of India
- UPSC: Previous year question papers
Editorial Disclaimer
This article explains the types of ATM in India for UPSC preparation from the Reserve Bank of India's circulars, FAQs and statistics. Figures are as stated in the cited documents. Colour labels other than white and brown are not RBI categories.


